Juan José Vilatela and Miguel Ángel Rodiel, IMDEA MATERIALS
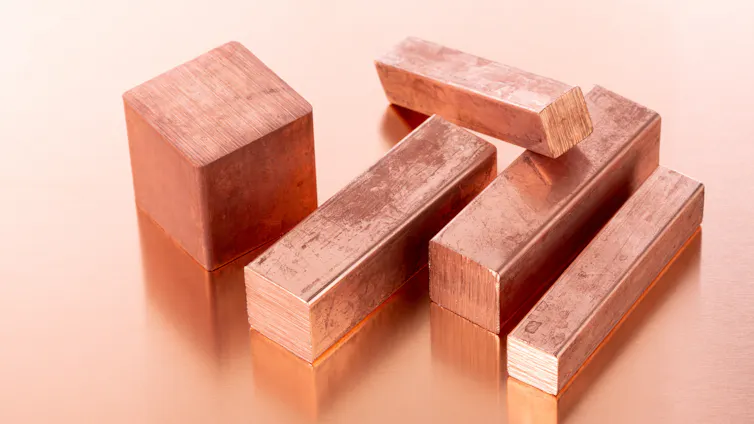
If we want to reduce our dependence on fossil fuels, we need to electrify a large part of the economy, and that requires enormous quantities of a material whose supply cannot grow at the same pace: copper. Added to this pressure is the growing demand from AI-driven data centers. In materials laboratories around the world, researchers are racing against time to find alternatives. We have recently contributed a new formula that opens the door to lighter electrical conductors capable of complementing copper in the applications required by the development of artificial intelligence.
The Global Copper Deficit
In 2025, global refined copper consumption reached approximately 28.2 million tonnes. By 2040, the annual deficit in the primary supply of this material is expected to reach 10 million tonnes.
In fact, in November 2025, the United States officially added copper to its list of 60 critical minerals, and since 2000 its price has risen from $2 per kilogram to $14 per kilogram. This year alone, the price has increased by 40%. A material does not need to be geologically rare to become strategic. It only needs to be indispensable and impossible to supply at the required rate.
Artificial Intelligence Also Needs Copper
Alongside the electrification of transport, renewable energy deployment, and power grids, a new major consumer of electricity has emerged: artificial intelligence and data centers.
The International Energy Agency (IEA) estimates that global electricity consumption by data centers could exceed 945 terawatt-hours (TWh) by 2030, more than double the level recorded in 2024 and slightly higher than Japan’s current total electricity consumption. Artificial intelligence will be the main driver of this growth.
But data centers do not only consume electricity. They also require large amounts of copper in cables, busbars, transformers, power supply systems, cooling equipment, and electrical connections.
S&P Global Ratings, a leading authority in market, energy, and commodities analysis, estimates a typical copper intensity of 30-40 tonnes per megawatt (t/MW) installed in modern data centers. In some facilities dedicated specifically to AI training, this figure can approach 47 t/MW. As a result, a large 1-gigawatt (GW) data center could require tens of thousands of tonnes of copper for its own infrastructure alone. This does not include the copper needed for power generation and the transmission and distribution networks that supply it.
According to the same study, annual copper demand associated with data centers could rise from 1.1 million tonnes in 2025 to 2.5 million tonnes in 2040, including approximately one million tonnes per year linked to renewable power generation and associated grid infrastructure. Artificial intelligence needs chips. But before that, it needs electricity and materials capable of carrying it.
Mining and Recycling Will Not Be Enough
The solution necessarily involves opening new mines, improving existing operations, and recycling much more copper. In fact, the IEA estimates that a strong expansion of recycling could reduce the need for new copper mines by as much as 40% by 2050.
However, the reality is that the proportion of recycled copper in total demand fell from 37% to 33% between 2015 and 2023, and that 40% target would only be achieved under a scenario in which national climate commitments are fully met. Rapidly increasing production is not easy. Ore grades, meaning the concentration of useful minerals in extracted rock, are declining, project costs are increasing, and developing a new mine takes an average of 17 years from discovery to production.
The question is no longer whether we will need more copper, but how we will meet the demand for electrical conductors with alternative materials capable of replacing it. Aluminum already serves this role in many power transmission lines. Its lower density partly compensates for its lower conductivity. For example, expanding the use of aluminum in certain underground and subsea cables could substantially reduce copper requirements.
But in light of current projections, it seems reasonable to think we must go further and design a new generation of conductors.
Carbon Moves from the Laboratory to Industrial Roadmaps
Carbon nanotube (CNT)-based materials are among the most promising candidates. For decades, we have known about the extraordinary properties of CNTs at the nanoscale. The real challenge, however, has been turning millions of nanotubes into continuous fibers that retain those properties at the macroscopic scale.
That leap, first achieved in laboratories, is now beginning to reach industry.
In the United States, DexMat, a spin-off from Rice University, markets Galvorn, a family of conductive CNT fibers developed from technology pioneered by Nobel laureate Richard Smalley. In South Korea, aweXome Ray, founded by researchers from Seoul National University and Seohyun TechChem, is scaling up continuous fibers and hybrid CNT-copper conductors for ultra-lightweight wiring.
Although the first CNT fibers were produced in Europe, the continent currently lacks manufacturers. Nevertheless, European companies and research groups remain active in developing applications and products based on carbon nanotube conductors.
A New Development
Research led by IMDEA Materials scientists, together with other Spanish institutions, and published in Science in 2026, presents a major advance in the race to develop industrial-scale non-metallic conductors.
By carefully introducing specific chemical elements, known as dopants, between perfectly aligned carbon nanotubes, we created a fiber visible to the naked eye that conducts electricity 17 times better than the original material. In fact, this new thread achieves nearly half the electrical conductivity of copper, the benchmark material used in today’s cables.
The most striking figure emerges when weight is taken into account. Its specific conductivity reaches 17,345 S·m²/kg, a measure of how much electricity a material can conduct relative to its weight, meaning how much conductivity is achieved per kilogram of mass. This value exceeds that of both copper and aluminum. In addition, the fibers combine these electrical properties with high mechanical strength.
Today, we cannot yet replace copper, as key challenges remain, including stability, scalability, and industrialization. However, our research demonstrates that the gap between the properties of CNTs at the nanoscale and those of a useful macroscopic conductor can be dramatically reduced. This opens a pathway for carbon nanotube fibers, already being produced at industrial scale, to be used as conductors in large-scale strategic applications. That is where the potential paradigm shift lies.
A Matter of Economic Security
There is unlikely to be a single solution to the supply tensions that lie ahead.
Aluminum will take over a larger share of certain applications. Increased recycling will reduce the need for primary raw materials. Better engineering designs will reduce the amount of conductive metal required. And, of course, new families of conductive materials, such as those based on carbon nanotubes, will enter the market.
But one conclusion is becoming increasingly difficult to ignore: a far more electrified and digital global economy cannot indefinitely depend on virtually the same portfolio of conductive materials that we used a century ago, especially when many of those materials are now classified as critical.
Developing the next generation of conductors is not merely a challenge in materials science. It is a matter of economic security, technological autonomy, and our ability to make both the energy transition and the digital transition possible.
Juan José Vilatela, Principal Investigator, IMDEA MATERIALS and Miguel Ángel Rodiel, Technology Director, IMDEA MATERIALS
This article was originally published in The Conversation. Read the original.